
Stamp Duty
UK stamp duty calculator: SDLT, LBTT and LTT.
Estimate the property-purchase tax due in England and Northern Ireland (SDLT), Scotland (LBTT) and Wales (LTT). Supports first-time buyers and the additional-dwelling surcharge.
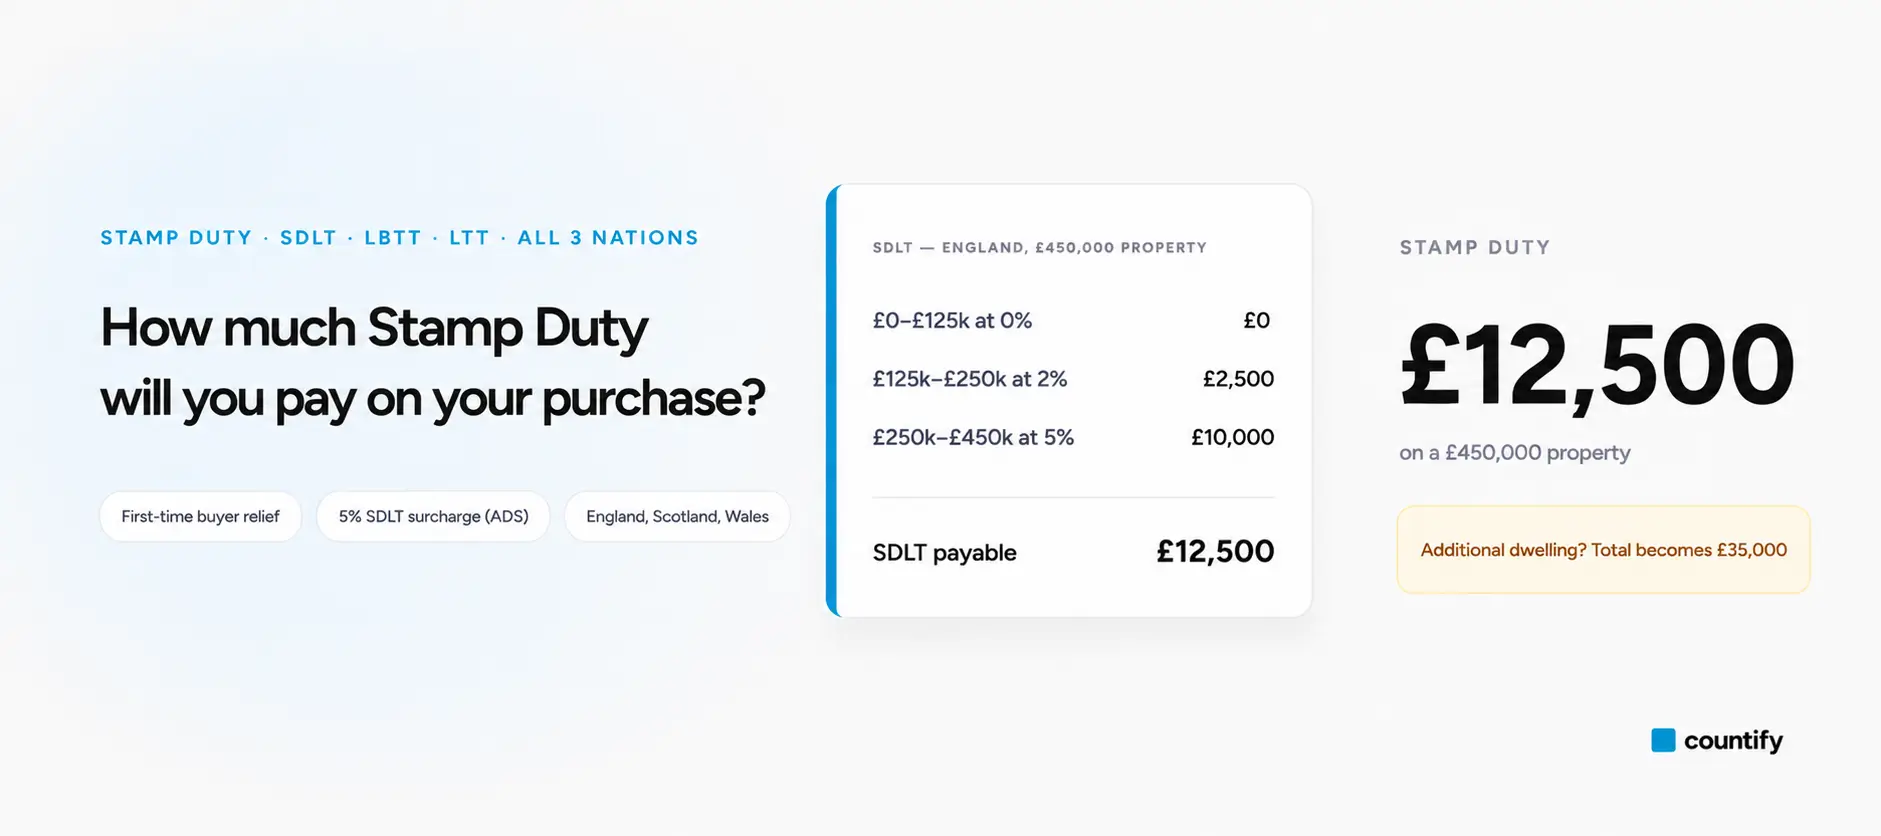
Property-purchase tax depends on the nation. In England and Northern Ireland, Stamp Duty Land Tax (SDLT) is 0% up to £125,000, 2% to £250,000 and 5% to £925,000. In Scotland, LBTT starts at 0% up to £145,000; in Wales, LTT starts at 0% up to £225,000. First-time-buyer relief and the additional-dwelling surcharge change these rates — the calculator applies the correct bands for your nation and buyer type.
Reviewed by Kamran Ishaq FCCA, Founder & CEO · Last updated
SDLT payable
£5,000
Effective rate 1.7% on £300,000
Band-by-band breakdown
- £0 – £125,000 at 0%£125,000.00 → £0.00
- £125,000 – £250,000 at 2%£125,000.00 → £2,500.00
- £250,000 – £925,000 at 5%£50,000.00 → £2,500.00
Buying property in Scotland?
Scotland uses LBTT rather than SDLT. For Scottish residential and commercial rates, first-time buyer relief, worked house-price examples and the 8% Additional Dwelling Supplement, use the dedicated Scottish stamp duty and LBTT calculator.
Related calculators
Keep planning.
Scottish Property Tax
LBTT Calculator Scotland
Scottish LBTT band by band, with first-time buyer relief, 8% ADS and commercial rates.
Capital Gains
Capital Gains Tax Calculator
Residential vs other assets, £3,000 annual exempt amount, BADR included.
Property
Rental Income Tax Calculator
Section 24 mortgage interest credit, allowable expenses, higher-rate landlord impact.
Expert help
Turn your estimate into the right tax decision.
A calculator can model the numbers. Our accountants can check the assumptions, explain the options and handle the return or payroll work for you.
Ask an accountantQuestions
Frequently asked
questions.
From 1 April 2025 the residential SDLT bands reverted to pre-COVID levels: 0% to £125,000, 2% to £250,000, 5% to £925,000, 10% to £1.5m, and 12% above. First-time buyers pay 0% up to £300,000 and 5% on the slice between £300,000 and £500,000, with no relief if the price exceeds £500,000.
LBTT residential bands for 2026/27 are 0% to £145,000, 2% to £250,000, 5% to £325,000, 10% to £750,000 and 12% above. First-time buyers pay 0% up to £175,000. The Additional Dwelling Supplement (ADS) is 8% on second homes and buy-to-let purchases since 5 December 2024.
Wales has no first-time buyer relief but a higher 0% threshold of £225,000. The next slice to £400,000 is 6%, then 7.5% to £750,000, 10% to £1.5m and 12% above. Additional-dwelling LTT starts at 5% from the first pound and rises through six bands.
SDLT returns and payment in England and Northern Ireland are due within 14 days of completion. LBTT (Scotland) and LTT (Wales) are due within 30 days. Returns are filed by your conveyancer, who deducts the duty from completion funds.
Yes. Limited companies pay HRAD / ADS on residential property regardless of the number of dwellings owned. From £500,000, companies acquiring single residential dwellings also fall within the 17% flat SDLT charge unless a relief (e.g. property rental business) applies.
Get started
Take control of your
numbers today.
Free, no-obligation consultation. We agree the fee upfront — no surprises.
5.0 on Google · 8 reviews- Fixed fee agreed in writing before work starts — no surprise bills.
- Switching is handled for you, including the professional clearance letter.
- A named accountant who knows your business, not a call queue.