
HMRC penalties
HMRC late payment interest, interest rates and penalties calculator (2026).
Estimate HMRC late payment interest at 7.75% per annum and fixed penalties for late Self Assessment, Corporation Tax, VAT or PAYE filings and payments.
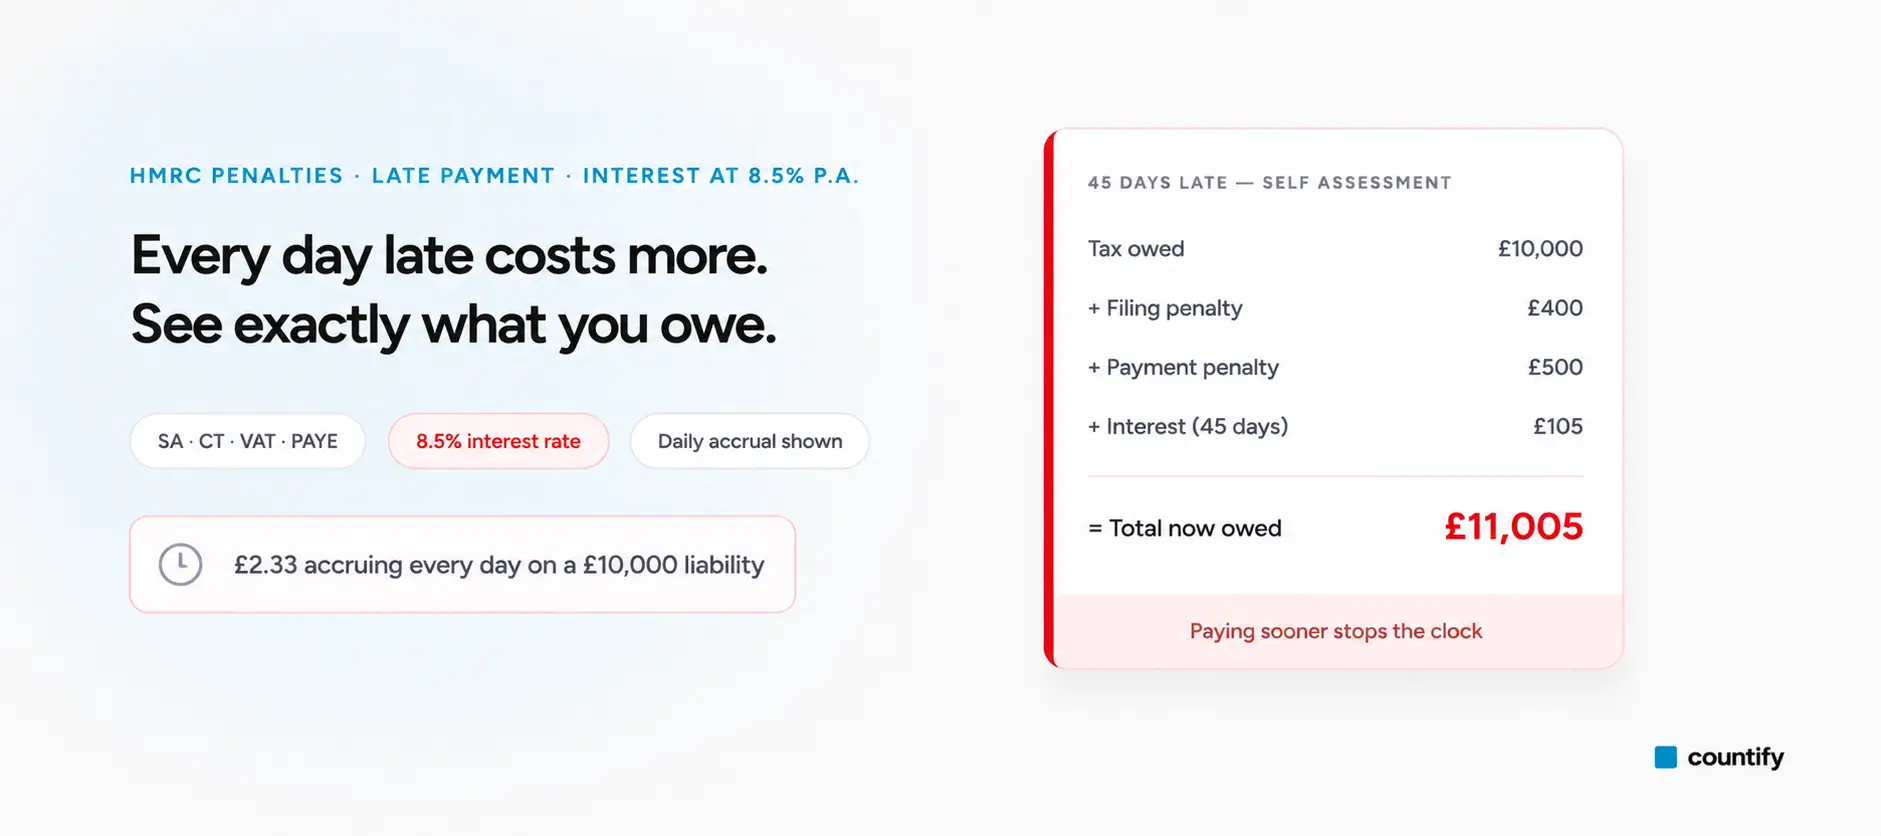
To calculate HMRC late-payment interest, multiply the unpaid tax by the annual interest rate, multiply by the number of days late, then divide by 365. At the current 7.75% rate, £5,000 overdue for 30 days produces about £31.85 of simple interest. Interest normally runs from the payment due date until HMRC receives payment; filing and late-payment penalties are separate. This calculator estimates both for 2026.
Reviewed by Kamran Ishaq FCCA, Founder & CEO · Last updated
Total now owed
£5,382
Includes tax, penalties and late payment interest
Additional cost
£381.85
- Filing penalty
- £100
- Payment penalty
- £250
- Interest charged
- £32
Daily interest accruing
£1.06/day
Using the rate reviewed on 25 September 2026.
Full breakdown
- Tax owed£5,000.00
- + Filing penalty£100.00
- + Late payment penalty£250.00
- + Interest (30 days at 7.75%)£31.85
- = Total owed£5,381.85
This is an estimate for guidance only. HMRC's actual assessment may differ. Contact Countify immediately if you have an overdue tax liability.
Source: gov.uk HMRC interest rates. Rates verified 25 September 2026.
That's £382 in penalties and interest so far, and it keeps growing until HMRC is up to date. Talk to us today and we'll stop the clock.
Calculation guide
How to calculate late payment interest.
HMRC late-payment interest is simple interest, calculated daily on the outstanding tax. It is separate from late-filing and late-payment penalties.
Formula
Unpaid tax × annual rate × days late ÷ 365
Using the current 7.75% annual rate: £5,000 × 0.0775 × 30 ÷ 365 = £31.85 of interest.
- Step 01
Find the balance
Use the tax still unpaid after any part-payments or credits.
- Step 02
Count late days
Use the number of days from the relevant due date to the payment date.
- Step 03
Apply each rate
HMRC's rate changes with the base rate. Enter the due date above and the calculator splits the period at every change.
HMRC's rate is linked to the Bank of England base rate and can change. Enter the due date in the calculator and it applies the rate for each part of the overdue period, from HMRC's published history below. Check the official HMRC interest-rate tables before relying on a figure.
Rate history
HMRC interest rates since 2020.
HMRC's late payment and repayment interest rates for Income Tax, National Insurance, Capital Gains Tax, Stamp Duty Land Tax and VAT, with the Bank of England base rate each is set from. Late payment interest moved from base rate plus 2.5% to base rate plus 4% on 6 April 2025.
| From | Base rate | Late payment | Repayment |
|---|---|---|---|
| 9 January 2026 | 3.75% | 7.75% | 2.75% |
| 27 August 2025 | 4.00% | 8.00% | 3.00% |
| 28 May 2025 | 4.25% | 8.25% | 3.25% |
| 6 April 2025 | 4.50% | 8.50% | 3.50% |
| 25 February 2025 | 4.50% | 7.00% | 3.50% |
| 26 November 2024 | 4.75% | 7.25% | 3.75% |
| 20 August 2024 | 5.00% | 7.50% | 4.00% |
| 22 August 2023 | 5.25% | 7.75% | 4.25% |
| 11 July 2023 | 5.00% | 7.50% | 4.00% |
| 31 May 2023 | 4.50% | 7.00% | 3.50% |
| 13 April 2023 | 4.25% | 6.75% | 3.25% |
| 21 February 2023 | 4.00% | 6.50% | 3.00% |
| 6 January 2023 | 3.50% | 6.00% | 2.50% |
| 22 November 2022 | 3.00% | 5.50% | 2.00% |
| 11 October 2022 | 2.25% | 4.75% | 1.25% |
| 23 August 2022 | 1.75% | 4.25% | 0.75% |
| 5 July 2022 | 1.25% | 3.75% | 0.50% |
| 24 May 2022 | 1.00% | 3.50% | 0.50% |
| 5 April 2022 | 0.75% | 3.25% | 0.50% |
| 21 February 2022 | 0.50% | 3.00% | 0.50% |
| 7 January 2022 | 0.25% | 2.75% | 0.50% |
| 7 April 2020 | 0.10% | 2.60% | 0.50% |
| 30 March 2020 | 0.25% | 2.75% | 0.50% |
Source: HMRC interest rates for late and early payments, GOV.UK. VAT uses these rates for accounting periods starting on or after 1 January 2023.
Related calculators
Keep planning.
Deadlines
Tax Deadline Checker
Self-Assessment, VAT, CT600, P11D and Confirmation Statement — late-filing exposure.
HMRC Compliance
HMRC Enquiry Risk Checker
Score your HMRC enquiry risk based on sector, expenses, turnover pattern and filing history.
VAT
VAT Calculator
Add, remove and reverse VAT at 20%, 5% or 0%. Includes the Flat Rate Scheme.
Expert help
Need help with an overdue HMRC bill or penalty?
We can check the calculation, review appeal grounds and help you respond to HMRC before further interest or penalties build up.
Ask about HMRC supportQuestions
Frequently asked
questions.
Use the formula: unpaid tax × annual interest rate × days late ÷ 365. At 7.75%, £5,000 paid 30 days late gives £31.85 of simple interest. If HMRC changes its rate during the overdue period, split the calculation into separate date ranges and use the rate that applied to each range. Penalties are calculated separately.
HMRC charges 7.75% a year simple interest from the payment due date. HMRC interest rates are linked to the Bank of England base rate: late payment interest is base rate plus 4% (raised from base plus 2.5% on 6 April 2025), and it changes automatically whenever the base rate moves.
When HMRC repays tax you overpaid, it adds repayment interest at base rate minus 1%, with a minimum of 0.5% — currently 2.75% a year. Interest paid by HMRC runs from the later of the payment date and the original due date until the repayment is made. The gap between the two rates is deliberate: it makes paying late costly and leaving money with HMRC unattractive.
Paying Corporation Tax late costs interest, not a percentage penalty: HMRC charges late payment interest at 7.75% a year from the day after the payment deadline — 9 months and 1 day after the end of the accounting period — until the day it is paid. Penalties for Corporation Tax come from filing the CT600 late, and rise at 3, 6 and 12 months. Large companies paying by quarterly instalments are charged 6.25% on late instalments until the normal due date, and HMRC pays 3.50% on instalments paid early or overpaid. Choose Corporation Tax in the calculator to see both.
There is no penalty if the VAT is paid within 15 days of the due date. Paid between 16 and 30 days late, the penalty is 3% of the VAT outstanding at day 15. After 30 days it becomes 3% of the amount outstanding at day 15 plus 3% of the amount outstanding at day 30, and a second penalty then accrues daily at 10% a year until the VAT is paid. Late payment interest at 7.75% a year runs on top from the due date.
Usually, yes. HMRC offers payment plans for overdue tax, which you can check your eligibility for and set up online, or by contacting HMRC. It checks affordability: you will normally be asked to pay about half of what is left each month after rent, food, bills and fixed outgoings, and there is no set time limit on the plan. Late payment interest keeps running on the unpaid balance, so paying faster costs less in total. Free debt advice is available from MoneyHelper in England and Wales and Scotland Debt Solutions in Scotland.
Yes, if you have a reasonable excuse such as serious illness, bereavement or HMRC delays. Countify can prepare and submit a penalty appeal.
The Self Assessment late filing penalty is £100 immediately, plus £10 per day after 3 months up to £900, plus 5% of tax or £300 after 6 and 12 months.
Penalties are fixed amounts at set milestones. Interest is charged at a simple daily rate on the outstanding tax. They do not compound on each other.
For most tax payments, interest runs from the day after the payment due date until the date HMRC receives the payment. Special rules can apply to some liabilities, and interest continues on any balance left unpaid after a part-payment or Time to Pay arrangement.
As soon as possible. Every day adds to the interest charge, and even a part-payment reduces the amount on which interest accrues.
HMRC charges £100 per 50 employees for each month (or part month) a P11D or P11D(b) is filed late, plus interest on any Class 1A National Insurance paid late — calculated the same way as the late payment interest above. The filing deadline is 6 July after the tax year end, with payment due by 22 July (19 July if paying by cheque).
Yes. Interest on tax settled through a disclosure facility (such as the Worldwide Disclosure Facility) runs from each year's original due date to the date of payment, using the same simple daily-rate method as any other late payment — it just typically covers several tax years at once, so the total can be substantial even at a modest annual rate.
Get started
Take control of your
numbers today.
Free, no-obligation consultation. We agree the fee upfront — no surprises.
5.0 on Google · 8 reviews- Fixed fee agreed in writing before work starts — no surprise bills.
- Switching is handled for you, including the professional clearance letter.
- A named accountant who knows your business, not a call queue.